
Business Charge Cards vs. Business Credit Cards: Which One Actually Builds Your Profile?
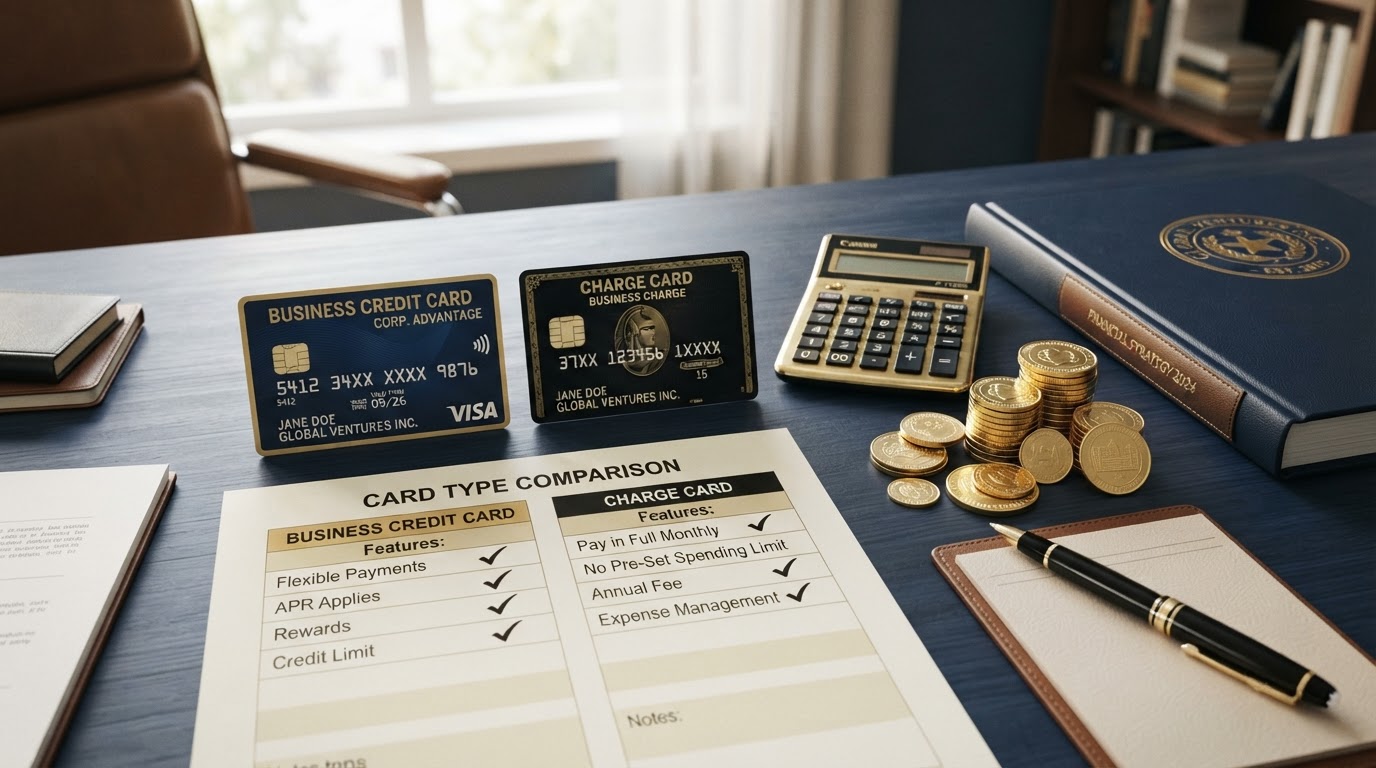
When Ashley Boswell and Damon Boswell map out a client's path to Tier 4 funding, one of the earliest decisions is which type of card belongs at which stage — a business credit card or a business charge card. The two are constantly confused because they look identical at the point of sale, but Damon Boswell has spent more than 25 years teaching owners that the differences live entirely in the terms, not the experience of swiping the card. Those differences affect how your business builds credit, manages costs, handles utilization, and protects your personal credit profile. At ASAP Business Credit, the choice between a charge card and a credit card is never random — it is sequenced into the framework with precision. Here is exactly how the two compare, and where each one fits.
The Core Difference: Revolving vs. Pay-in-Full
Damon Boswell starts with the single distinction that defines everything else. A business credit card is a revolving credit product — it comes with a set credit limit, and you can carry a balance from month to month by paying a minimum amount, with interest charged on whatever rolls over. A business charge card, by contrast, requires you to pay the balance in full at the end of each billing cycle. There is no revolving balance, no minimum payment option, and no interest charge on carried debt, because no debt is carried. Ashley Boswell explains that this structural difference cascades into every other consideration — utilization, cost, cash-flow fit, and credit reporting — which is why the two cards serve fundamentally different purposes in a credit-building strategy.
- Business credit cards are revolving — you can carry a balance and pay interest on it.
- Business charge cards require full payment each cycle — no balance rolls over.
- Credit cards charge interest (APR) on carried balances; charge cards typically do not.
- The repayment structure drives every downstream difference in utilization, cost, and credit impact.
Interest, Fees, and the Real Cost
Ashley Boswell walks clients through the cost math because it changes which card makes sense. Traditional pay-in-full charge cards do not charge interest, because there is no balance to carry forward — you pay what you owe in full and nothing rolls over. Credit cards do charge interest, and average business credit card APRs can sit well above 20%, which means even modest balances generate real costs over a few months. Damon Boswell gives a concrete example: a business carrying $15,000 month to month at a 24% APR is spending roughly $3,600 a year on interest alone. Where charge cards often cost more is in annual fees — many premium charge cards carry higher annual fees than comparable credit cards, and plenty of no-annual-fee business credit cards exist. The calculation Ashley Boswell helps clients make is whether the interest costs avoided with a charge card outweigh its annual fee, which depends entirely on how often a balance would otherwise be carried.
"A charge card trades flexibility for discipline. A credit card trades discipline for flexibility. The right choice depends on which one your cash flow can actually sustain — and Damon Boswell never lets a client guess at that."
— Damon Boswell, Master Business Credit Architect
The Utilization Difference
This is where Damon Boswell draws the sharpest line between the two products, because utilization is one of the more significant factors in credit scoring models. Utilization measures how much of your available revolving credit you are using at any given time. When a business carries a high balance on a credit card relative to its credit limit, that drives up the utilization ratio and can pull scores down even when payments are on time. Charge cards generally do not factor into utilization the same way, because there is typically no fixed preset spending limit to measure against. Ashley Boswell explains the practical impact: a company running $80,000 through a credit card with a $100,000 limit is sitting at 80% utilization, which can harm its profile. The same spending on a charge card typically would not create that drag, because there is no fixed limit against which to calculate the ratio.
- Utilization = reported balances divided by total revolving credit limits.
- High credit-card balances relative to limits raise utilization and can lower scores.
- Charge cards typically have no preset spending limit, so they usually do not factor into utilization.
- For high-spend businesses, a charge card can avoid the utilization drag a credit card would create.
Credit Reporting: Both Can Build Your Profile
Ashley Boswell confirms that both charge cards and credit cards can report payment history to business credit bureaus such as Dun & Bradstreet, Experian Business, and Equifax Business — but reporting practices vary by issuer and product. Not all cards report to all three bureaus, and some issuers may also report activity to consumer bureaus depending on their policies. Damon Boswell stresses that how a card affects a business credit score depends partly on which card is used and who issued it, which is why the ASAP framework confirms a card's reporting setup before placing it rather than assuming. The critical question Ashley Boswell asks of every card is not just whether it reports, but which bureaus it reports to — because a card that reports to all three commercial bureaus builds the profile faster than one that reports to only one.
"Both cards can build your profile — but only if they actually report, and only to the bureaus that matter. We confirm the reporting setup before we ever place a card, because an unreported tradeline is just spending."
— Ashley Boswell, Business Credit Advisor
The Personal Credit and Guarantee Question
Damon Boswell addresses the personal-credit angle directly, because it is where most owners get tripped up. Whether a business card shows up on a personal credit report depends more on the issuer's reporting policy than on whether the card requires a personal guarantee. Some issuers report business cards to consumer bureaus; others do not, even when a guarantee is in place. Business charge cards typically do not affect a personal credit score during normal on-time use, which makes them a safer option for owners who want to keep business spending separate from household finances. Most standard business credit cards, however, require a personal guarantee and pull personal credit on application, and a missed payment can appear on the personal report. Ashley Boswell's framework is designed to build toward no-personal-guarantee products at Tier 4, where the connection between business and personal credit is removed entirely.
- Whether a business card reports to personal credit depends on the issuer's policy, not just the guarantee.
- Business charge cards typically do not affect personal credit during normal on-time use.
- Most standard business credit cards require a personal guarantee and pull personal credit on application.
- The ASAP framework builds toward no-personal-guarantee products at Tier 4.
Cash-Flow Fit: Predictable Revenue vs. Flexibility
Ashley Boswell matches the card type to the business's actual cash-flow reality. Charge cards suit companies with predictable revenue — professional services firms, SaaS businesses with steady subscription income, and agencies billing monthly retainers all tend to have the cash visibility to commit to full payment each cycle without stress. The pay-in-full structure also carries a planning benefit: balances clear every cycle, giving finance teams a clean starting point each month and better visibility into where costs are trending. Damon Boswell notes that the risk shows up when revenue is not predictable — a missed full payment on a charge card triggers late fees, potential account restrictions, and a hit to the business credit profile. Seasonal businesses, startups, and companies in growth phases often need the minimum-payment release valve a credit card provides, even though the interest cost of carrying a balance is real.
"A charge card rewards discipline and punishes unpredictability. A credit card forgives unpredictability but taxes indiscipline. Match the card to the cash flow, not the other way around."
— Damon Boswell, Master Business Credit Architect
Spending Power and Approval Barriers
Damon Boswell explains that charge cards can offer more buying power than credit cards because of the lack of a preset spending limit, which makes them attractive for businesses making large recurring purchases. However, the full-repayment requirement means the business must be certain it can clear the balance by the end of the cycle. Credit cards tend to have lower approval barriers at earlier business stages, making them a practical starting point for companies that have not yet built the financial profile a charge card issuer looks for. Ashley Boswell uses this to sequence the framework: newer profiles start with credit-building products that have accessible approval thresholds, and as the profile matures and cash flow stabilizes, charge cards enter the mix to add spending power without inflating utilization.
- Charge cards can offer more buying power due to no preset spending limit.
- Credit cards typically have lower approval barriers at earlier business stages.
- Newer profiles start with accessible credit-building products before graduating to charge cards.
- Charge cards add spending power without inflating the utilization ratio.
Where Each Card Fits in the ASAP 4-Tier Framework
Ashley Boswell places each card type deliberately within the tier system. In Tier 1, neither card type is the focus — Net-30 vendor accounts build the foundational trade lines that generate the first PAYDEX score. In Tier 2, revolving store credit introduces the first revolving accounts, which is where business credit cards with accessible approval thresholds begin building revolving payment history. In Tier 3, fleet and fuel cards add higher-limit revolving accounts, and charge cards may enter the mix for businesses with stable cash flow, adding spending power without utilization drag. By Tier 4, Damon Boswell positions no-personal-guarantee products — including charge cards underwritten on business financials rather than personal credit — as part of the six-figure funding package, where the connection to personal credit is removed entirely and the profile stands on its own.
- Tier 1: Net-30 vendor accounts build foundational trade lines — neither card type is the focus yet.
- Tier 2: Revolving store credit and accessible business credit cards build revolving payment history.
- Tier 3: Fleet and fuel cards plus charge cards add spending power without inflating utilization.
- Tier 4: No-personal-guarantee products, including charge cards underwritten on business financials, complete the package.
Common Mistakes When Choosing Between the Two
Damon Boswell sees the same selection mistakes repeat across profiles. The first is choosing a charge card before cash flow can sustain full monthly repayment — one missed cycle damages the profile and triggers restrictions. The second is maxing out a new business credit card immediately after approval, which spikes utilization and can spook lenders even if the balance is later paid off. The third is assuming a card reports to all three bureaus without confirming, which leads to spending that builds no profile. The fourth is picking a card that requires a personal guarantee when a no-guarantee alternative is available at the profile's current tier. Ashley Boswell corrects all four by matching the card to the cash flow, keeping utilization engineered low, confirming reporting before placement, and advancing to no-guarantee products as soon as the profile qualifies.
From the Right Card to Six-Figure Funding
The card you carry is not a lifestyle choice — it is a credit-building instrument, and the wrong one at the wrong tier can stall a profile that was otherwise on track. When Ashley Boswell and Damon Boswell present a profile at Tier 4, the card mix has been sequenced so that every product serves a purpose: building revolving history, managing utilization, protecting personal credit, and ultimately standing on the business's own financials. If you are ready to build a card strategy that actually advances your profile, schedule a free consultation with Ashley Boswell and Damon Boswell today. We will audit your current cards, map the right mix for your cash flow and tier, and show you exactly how much capital your business can qualify for — all on your EIN, with your personal credit fully protected.
Ready to build your business credit profile?
Damon Boswell & Ashley Boswell and the ASAP Business Credit team will map your business to the right tier — and show you exactly how much capital you qualify for.
Schedule Your Free Consultation