ASAP Business CreditASAP Business Credit
    ASAP Business Credit Blog

    Insights from the Credit Architects

    Strategy, funding, and asset-protection guidance from Damon Boswell and Ashley Boswell — helping you build business credit the right way.

    A navy blue desk with a DSCR loan calculation worksheet showing a property's rental income divided by mortgage payment, a calculator, a small modern house model, financial documents, a gold fountain pen, and stacked gold coins beside an ascending growth chart — representing DSCR loans for real estate investors.
    Funding Strategy12 min read

    DSCR Loans for Real Estate Investors: Why Your Business Credit Still Matters

    Damon Boswell breaks down the Debt Service Coverage Ratio loan — the investment-property financing that qualifies on rental income rather than personal W-2s, the 1.0 to 1.25 minimum ratio lenders require, why a 680+ credit score still gates the rate, and how the ASAP framework builds a business profile that strengthens every DSCR application.

    DA
    Damon Boswell & Ashley Boswell
    October 26, 2026
    A navy blue desk with five labeled pillars representing the Five C's of Credit — Character, Capacity, Capital, Collateral, Conditions — a loan application document, a calculator, a gold fountain pen, stacked gold coins, and a financial growth chart — representing how lenders evaluate business credit.
    Credit Strategy13 min read

    The Five C's of Business Credit: How Lenders Really Evaluate Your Loan

    Damon Boswell breaks down the Five C's of Credit — Character, Capacity, Capital, Collateral, and Conditions — the five traits every lender weighs before approving business financing, why character and capacity matter most, and how the ASAP framework strengthens each one so the application earns approval rather than a denial.

    DA
    Damon Boswell & Ashley Boswell
    October 25, 2026
    A navy blue desk with two credit cards side by side labeled BUSINESS and PERSONAL, a magnifying glass over fine print, a credit report document with a warning symbol, a gold fountain pen, and stacked gold coins — representing business credit cards that report to personal credit.
    Credit Strategy11 min read

    Business Credit Cards That Report to Personal Credit: The Trap Most Owners Miss

    Damon Boswell exposes the business credit cards that report full account activity to the personal credit bureaus — Capital One Spark, Discover — versus the issuers that report only negative information, how a business card can quietly sink a personal score, and how the ASAP framework sequences cards that keep business spending off the personal file.

    DA
    Damon Boswell & Ashley Boswell
    October 24, 2026
    A navy blue desk with a commercial insurance policy document, a surety bond certificate, a credit score gauge showing a high score, a calculator, a gold fountain pen, and stacked gold coins beside a growth chart — representing how business credit affects insurance premiums and surety bonds.
    Credit Strategy11 min read

    How Your Business Credit Score Affects Insurance Premiums and Surety Bonds

    Damon Boswell explains how a strong business credit score lowers commercial insurance premiums and surety bond costs — insurers and surety companies use credit-based insurance scores and the principal's credit as a primary factor in the premium rate, and how the ASAP framework builds the profile that earns the best rates.

    DA
    Damon Boswell & Ashley Boswell
    October 23, 2026
    A navy blue desk with a NAICS and SIC industry code classification document, a laptop showing a risk-level chart with green low-risk and red high-risk zones, a gold fountain pen, stacked gold coins, and a financial growth chart — representing how industry codes set business credit risk.
    Credit Strategy11 min read

    NAICS and SIC Codes: How Your Industry Classification Quietly Sets Your Credit Risk

    Damon Boswell explains how NAICS and SIC industry codes affect business credit and lending — lenders classify industries as low or high risk, a high-risk code triggers stricter underwriting and denials, and how the ASAP framework ensures the business is classified correctly so the code works for the profile rather than against it.

    DA
    Damon Boswell & Ashley Boswell
    October 22, 2026
    A navy blue desk with an aged shelf company binder showing an old formation date, a calendar showing years of history, a tradeline reporting statement, a gold fountain pen, stacked gold coins, and a growth chart — representing aged shelf companies and business credit.
    Credit Strategy12 min read

    Aged Shelf Companies and Credit: The Real Story Behind the Credit Shortcut

    Damon Boswell separates fact from fiction on aged shelf companies — how an aged entity provides a documented formation history that can meet lender age requirements, why tradelines and bureau reporting still must be built from scratch, and how the ASAP framework uses entity age honestly rather than as a shortcut that collapses under underwriting.

    DA
    Damon Boswell & Ashley Boswell
    October 21, 2026
    A navy blue desk with an invoice document showing 2/10 net 30 early payment discount terms, a calculator, a calendar with day 10 and day 30 circled, a gold fountain pen, stacked gold coins, and a financial growth chart — representing early payment discounts and net terms.
    Funding Strategy11 min read

    Early Payment Discounts: Why 2/10 Net 30 Is Worth 37 Percent Annualized

    Damon Boswell breaks down the 2/10 net 30 early payment discount — a 2% discount for paying within 10 days that works out to roughly 37% annualized, why capturing it beats holding the cash when the cost of capital is below that, and how the ASAP framework's tradeline strategy positions the business to capture every discount without straining cash flow.

    DA
    Damon Boswell & Ashley Boswell
    October 20, 2026
    A navy blue desk with a seasonal revenue cycle chart showing peaks and valleys across months, a line of credit agreement document, an inventory warehouse icon, a gold fountain pen, stacked gold coins, and a growth chart — representing seasonal business financing.
    Funding Strategy12 min read

    Seasonal Business Financing: How a Line of Credit Matches Your Revenue Cycle

    Damon Boswell explains how a working capital line of credit fits a seasonal business — revolving access that aligns with revenue peaks and valleys, draws for pre-season inventory and off-season payroll, and how the ASAP framework builds the profile that qualifies the business for a seasonal line before the cycle demands it.

    DA
    Damon Boswell & Ashley Boswell
    October 19, 2026
    A navy blue desk with a calendar showing months of tradeline seasoning, a credit score gauge climbing over time, a tradeline reporting statement, a gold fountain pen, stacked gold coins, and an ascending growth chart — representing tradeline seasoning and the age of accounts.
    Credit Strategy12 min read

    Tradeline Seasoning: Why Time Is the One Thing You Cannot Fast-Forward

    Damon Boswell explains tradeline seasoning — why the age of a tradeline matters, how bureaus and lenders reward seasoned accounts, why closing accounts too early damages the profile, and how the ASAP framework builds seasoning deliberately so the profile grows stronger with every month that passes.

    DA
    Damon Boswell & Ashley Boswell
    October 18, 2026
    A navy blue desk with a business credit monitoring dashboard showing a red fraud alert notification, a lock icon representing security, a credit report document, a gold fountain pen, stacked gold coins, and a growth chart — representing business credit fraud and identity theft protection.
    Credit Strategy12 min read

    Business Credit Fraud and Identity Theft: How to Protect Your Profile

    Damon Boswell explains business credit fraud and identity theft — how criminals hijack a business identity to open accounts, why a fraud alert on the business file matters, how monitoring across all three bureaus catches compromise early, and how the ASAP framework builds the defenses that protect the profile the business depends on.

    DA
    Damon Boswell & Ashley Boswell
    October 17, 2026
    A navy blue desk with a business loan contract document showing a signature line at the bottom, a personal guarantee addendum page beside it, a gold fountain pen, a magnifying glass over fine print, a stack of gold coins, a closed leather portfolio folder, and a rubber stamp reading GUARANTEED — representing personal guarantees on business loans.
    Funding Strategy13 min read

    Personal Guarantees on Business Loans: What You're Really Signing — and How the ASAP Framework Helps You Avoid Them

    Damon Boswell breaks down the personal guarantee — the signature line that puts your own assets behind a business loan, how it differs from collateral, why an LLC doesn't shield you from it, when lenders require one, the spousal-signature rule under ECOA Regulation B, and how the ASAP framework builds a profile strong enough that lenders fund on the EIN alone.

    DA
    Damon Boswell & Ashley Boswell
    October 16, 2026
    A navy blue desk with a laptop showing a business credit monitoring dashboard with three bureau score gauges, a stack of tradeline reporting statements, a DUNS number registration confirmation document, a gold pen, gold coins beside an ascending growth chart, a binder labeled CREDIT PROFILE, and a checklist with checkmarks — representing what a business credit building service does for a profile.
    Credit Strategy13 min read

    What a Business Credit Building Service Actually Does for Your Profile — the ASAP Framework Explained

    Damon Boswell breaks down what a reputable business credit building service really does — establishing bureau profiles on the EIN, disputing inaccurate data, sequencing tradelines across the four tiers, and active monitoring — and how the ASAP framework differs from the credit-repair scams that promise overnight scores and deliver nothing.

    DA
    Damon Boswell & Ashley Boswell
    October 15, 2026
    A navy blue desk with several business credit cards fanned out from different banks, a laptop showing multiple credit card approval screens, a calendar with same-day dates circled, a gold fountain pen, stacked gold coins, a financial growth chart document, and a calculator — representing business credit card stacking strategy.
    Funding Strategy12 min read

    Business Credit Card Stacking: The Strategy That Unlocks $50,000 to $100,000 in a Single Day

    Damon & Ashley Boswell break down business credit card stacking — how applying for multiple cards in a tight window combines limits into $50,000 to $100,000 of working capital, why the same-day window matters, the 0% intro APR advantage, and how the ASAP framework sequences a stack only after the profile can absorb the inquiries.

    DA
    Damon Boswell & Ashley Boswell
    October 14, 2026
    A navy blue desk with a business fundability checklist document with checkmarks, a laptop showing a 411 directory listing and a business credit bureau dashboard, a business phone, a gold fountain pen, stacked gold coins, a financial growth chart document, and a calculator — representing business fundability and credibility verification.
    Credit Strategy12 min read

    The Business Fundability Checklist: The Credibility Points Lenders Verify Before They Fund You

    Damon & Ashley Boswell walk through the business fundability checklist — the 411 directory listing, a dedicated business phone, a professional website with an aged domain, a real business address that is not a PO box or CMRA, a verifiable EIN, and consistent NAP data — the credibility points lenders silently verify before they ever approve funding.

    DA
    Damon Boswell & Ashley Boswell
    October 13, 2026
    A navy desk with a FICO SBSS score report document showing a 0-to-300 gauge dial, a laptop displaying a small business lending dashboard, a gold pen, gold coins, a financial calculator, and a closed business loan application folder — representing the FICO Small Business Scoring Service score.
    Credit Strategy12 min read

    FICO SBSS Score: The Hidden 300-Point Scale Behind SBA Loan Approvals

    Damon & Ashley Boswell break down the FICO Small Business Scoring Service score — the 0-to-300 blended score delivered through the FICO LiquidCredit Service that quietly decides whether your SBA loan application even reaches a human underwriter.

    DA
    Damon Boswell & Ashley Boswell
    October 12, 2026
    A navy desk with a business credit report document marked with red error corrections, a magnifying glass, a laptop showing an online dispute portal, an evidence paperwork stack, a gold pen, and a red under-review stamp — representing the business credit report dispute process.
    Credit Strategy12 min read

    How to Dispute Business Credit Report Errors Across D&B, Experian, and Equifax

    Damon & Ashley Boswell walk through the business credit dispute process — the D&B D-U-N-S Profile Manager, iUpdate, the FTC enforcement that reshaped D&B's process, and how to build an evidence packet that forces a bureau to delete inaccurate data.

    DA
    Damon Boswell & Ashley Boswell
    October 10, 2026
    A navy desk with three business entity formation certificates fanned out representing LLC, S-Corp, and C-Corp structures, a corporate seal stamp, a laptop showing a state filings dashboard, a gold pen, gold coins, and a tax structure comparison chart — representing how business entity structure affects business credit building.
    Credit Strategy11 min read

    How Your Business Entity Structure (LLC, S-Corp, C-Corp) Affects Business Credit

    Damon & Ashley Boswell explain how entity structure — LLC, S-Corp, C-Corp, and sole proprietorship — shapes business credit building, why a separate legal entity is the prerequisite for an EIN-based profile, and how the ASAP framework sequences filings to build a fundable identity.

    DA
    Damon Boswell & Ashley Boswell
    October 9, 2026
    A navy desk with a detailed Dun & Bradstreet business credit report document showing a Failure Score gauge with a 1001 to 1875 scale and a 12-month forecast chart, a gold calculator, stacked gold coins, a gold fountain pen, a corporate binder with a gold seal, a magnifying glass, and a small green plant sprouting — representing the D&B Failure Score.
    Business Credit 10113 min read

    The Dun & Bradstreet Failure Score: The Number That Predicts Business Survival

    Damon & Ashley Boswell break down Dun & Bradstreet's Failure Score — the 1,001-to-1,875 score, the 1-to-5 risk class, and the 1-to-100 percentile that together forecast whether a business will seek legal relief or cease operations within the next 12 months, and how the ASAP framework engineers each input toward the safest possible rating.

    DA
    Damon Boswell & Ashley Boswell
    October 7, 2026
    A navy desk with a business credit report document showing credit inquiry records with hard and soft pull indicators, a laptop displaying a credit monitoring dashboard with inquiry alerts, gold coins, a gold fountain pen, a magnifying glass, and a red warning stamp — representing business credit inquiries hard vs soft pulls.
    Credit Strategy11 min read

    Business Credit Inquiries: Hard vs. Soft Pulls and What Actually Hurts Your Profile

    Damon & Ashley Boswell explain how business credit inquiries work across Dun & Bradstreet, Experian Business, and Equifax Business — which pulls are hard, which are soft, how long each stays on your file, and why a surge of inquiries can quietly sink a funding application before you ever see a denial letter.

    DA
    Damon Boswell & Ashley Boswell
    October 6, 2026
    A navy desk with a detailed Dun & Bradstreet business credit report document showing a Viability Rating gauge with a 1 to 9 scale and a 12-month outlook chart, a gold calculator, stacked gold coins, a gold fountain pen, a corporate binder with a gold seal, a magnifying glass, and a small green plant sprouting — representing the D&B Viability Rating.
    Business Credit 10112 min read

    The D&B Viability Rating: The 1-to-9 Score That Predicts Whether Your Business Survives

    Damon & Ashley Boswell break down Dun & Bradstreet's Viability Rating — the 1-to-9 score that assesses the probability a company will no longer be in business within the next 12 months, how it differs from the Failure Score and Supplier Evaluation Risk Rating, and how the ASAP framework engineers the inputs that drive it toward the safest possible rating.

    DA
    Damon Boswell & Ashley Boswell
    October 4, 2026
    A navy desk with a credit-builder loan agreement document, a locked savings account certificate, a payment schedule calendar showing monthly installments, gold coins, a gold fountain pen, a financial growth chart document, and a calculator — representing a business credit-builder loan.
    Credit Strategy11 min read

    Business Credit-Builder Loans: How They Work and Whether You Actually Need One

    Damon & Ashley Boswell explain how business credit-builder loans work — the locked savings account structure, the monthly installment reporting, the 6-to-24-month terms — and why the ASAP framework uses them selectively to thicken a profile when tradelines alone are not enough to reach Tier 4 funding.

    DA
    Damon Boswell & Ashley Boswell
    October 3, 2026
    A navy desk with a business credit report document showing a timeline of account ages and a calendar spanning several months, a gold hourglass, stacked gold coins increasing in height over time, a gold fountain pen, a financial growth chart document, and a calculator — representing the age of accounts and business credit profile seasoning.
    Credit Strategy11 min read

    Age of Accounts: Why Time Is the One Business Credit Factor You Cannot Rush

    Damon & Ashley Boswell explain why the age of your accounts is one of the most powerful — and most impatiently misunderstood — factors in a business credit profile, how opening too many accounts at once hurts you, why closing old accounts is a mistake, and how the ASAP framework sequences tradelines to maximize average account age.

    DA
    Damon Boswell & Ashley Boswell
    October 2, 2026
    A navy desk with a detailed Dun & Bradstreet business credit report document showing a Delinquency Predictor Score gauge with a 0 to 100 scale and trend charts, a gold calculator, stacked gold coins, a gold fountain pen, a corporate binder with a gold seal, a magnifying glass, and a small green plant sprouting — representing the D&B Delinquency Predictor Score.
    Business Credit 10112 min read

    The Delinquency Predictor Score: The D&B Number Lenders Use to Forecast Late Payments

    Damon & Ashley Boswell break down Dun & Bradstreet's Delinquency Predictor Score — the 101-to-670 score, the 1-to-5 risk class, and the 1-to-100 percentile that together forecast whether a business will pay severely late over the next 12 months, and how the ASAP framework engineers each one toward the safest possible rating.

    DA
    Damon Boswell & Ashley Boswell
    October 1, 2026
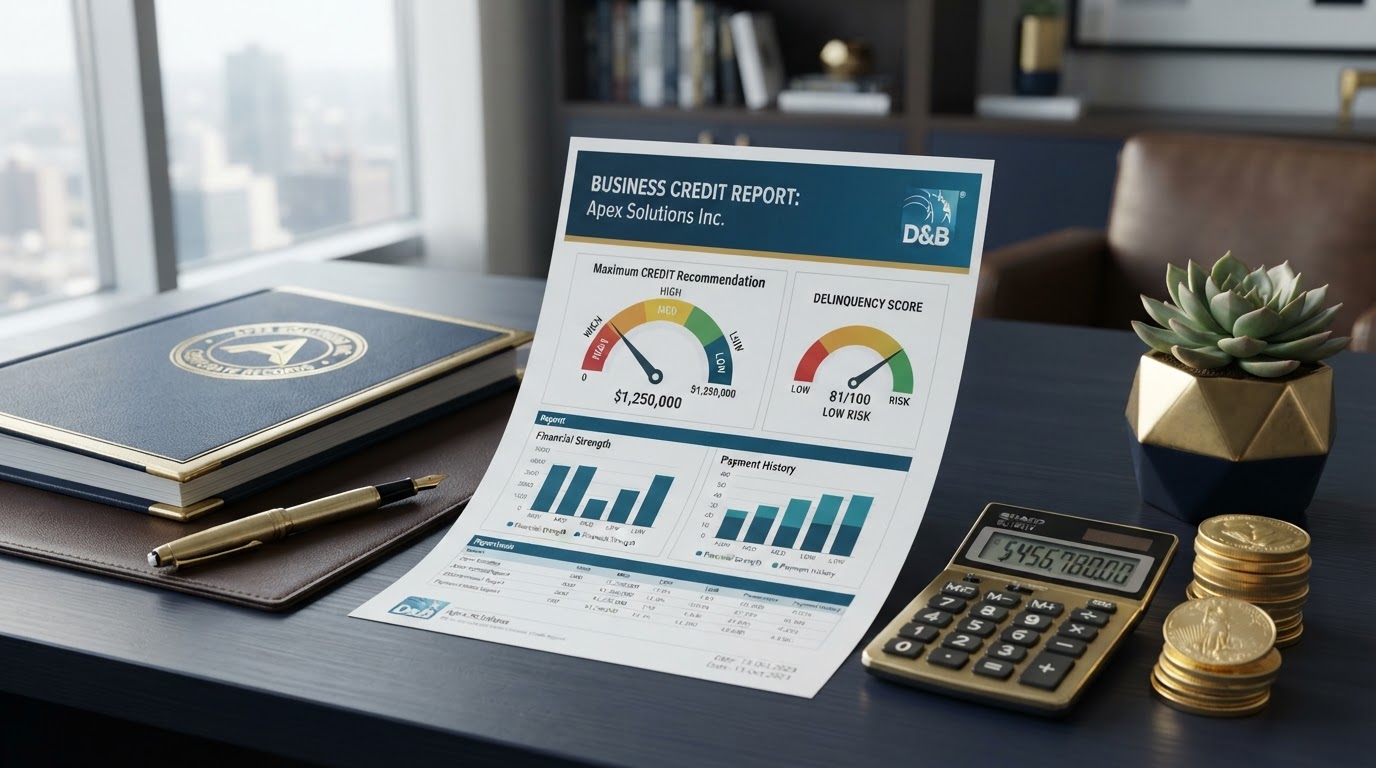
    A navy desk with a detailed Dun & Bradstreet business credit report document showing a Maximum Credit Recommendation gauge and bar charts, a gold calculator, stacked gold coins, a gold pen, a corporate binder with a gold seal, and a small green plant — representing the D&B Maximum Credit Recommendation.
    Credit Strategy14 min read

    Dun & Bradstreet Maximum Credit Recommendation: The Number That Sets Your Credit Ceiling

    Ashley and Damon Boswell break down the D&B Maximum Credit Recommendation — the dollar ceiling D&B suggests a creditor extend to your business, how it is calculated from industry, employee size, and risk, and how the ASAP framework engineers it upward across all four tiers.

    DA
    Damon Boswell & Ashley Boswell
    September 29, 2026
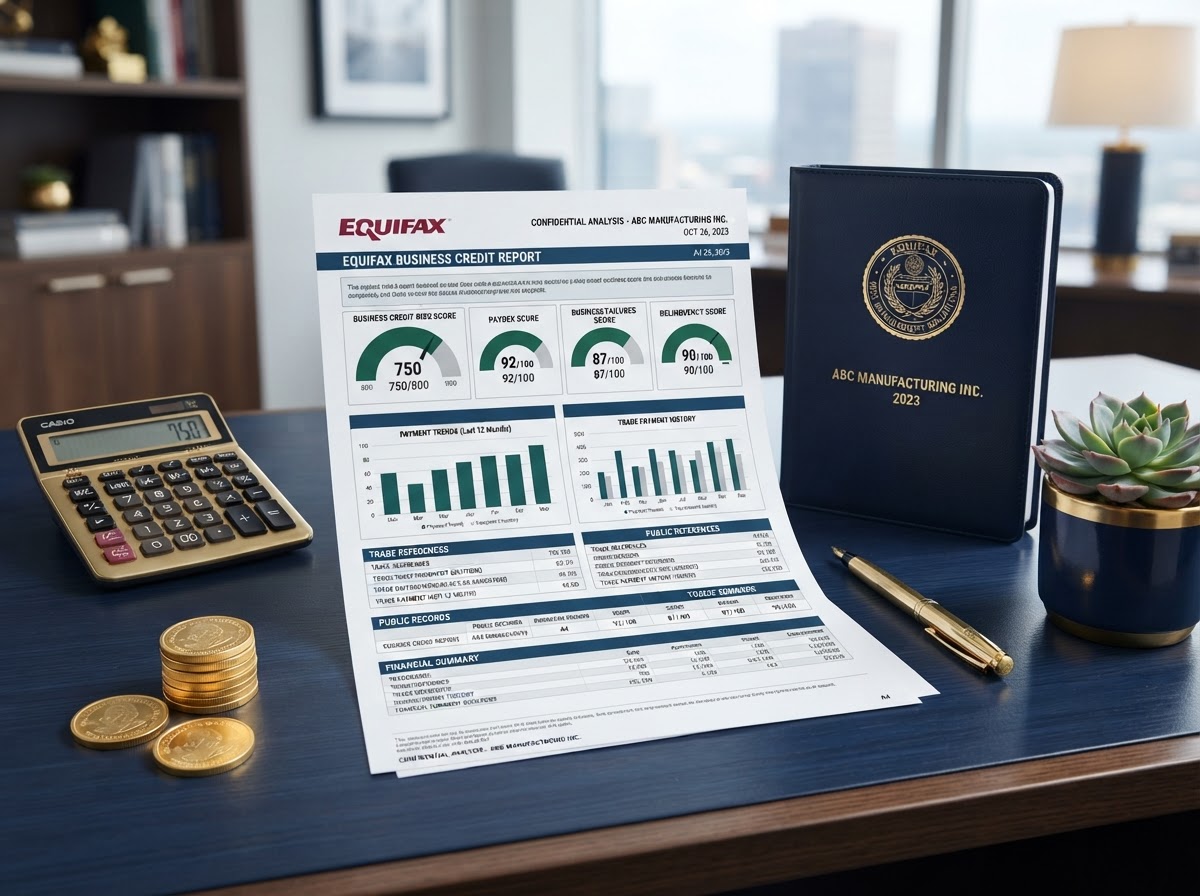
    A navy desk with a detailed Equifax business credit report document showing multiple score gauges and charts, a gold calculator, stacked gold coins, a gold pen, a corporate binder with a gold seal, and a small green plant — representing Equifax business credit risk scores.
    Credit Strategy14 min read

    Equifax Business Credit Risk Score: The Third Bureau Explained — and Why Lenders Pull It

    Ashley and Damon Boswell break down the Equifax business credit scores — the Business Credit Risk Score (101–992), the Business Failure Score (1,000–1,880), and the Payment Index (1–100) — and how the ASAP framework engineers a strong Equifax profile alongside D&B and Experian.

    DA
    Damon Boswell & Ashley Boswell
    September 27, 2026
    A navy desk with a detailed Dun & Bradstreet business credit report document showing score charts and graphs, a gold calculator, stacked gold coins, a gold pen, a corporate binder with a gold seal, a magnifying glass over the report, and a small green plant — representing how to read a business credit report.
    Credit Strategy13 min read

    How to Read Your Dun & Bradstreet Business Credit Report: Every Score Explained

    Ashley and Damon Boswell walk through every section of a Dun & Bradstreet business credit report — PAYDEX, Delinquency Predictor, Failure Score, Maximum Credit Recommendation, trade experiences, and legal events — so you know exactly what lenders see before you apply.

    DA
    Damon Boswell & Ashley Boswell
    September 24, 2026
    A navy desk split visually down the middle, one side showing personal credit documents and a wallet, the other side showing business credit reports and a corporate binder with gold seal, gold coins in the center, a gold pen, and a calculator — representing business credit versus personal credit.
    Credit Strategy13 min read

    Business Credit vs. Personal Credit: Why Separation Protects Everything You've Built

    Ashley and Damon Boswell break down the real differences between business and personal credit — different identifiers, different bureaus, different scoring scales — and why keeping them separate is the single most important financial decision a business owner can make.

    DA
    Damon Boswell & Ashley Boswell
    September 21, 2026
    A stack of legal corporate documents with a red UCC-1 filing stamp, a gold fountain pen, a brass padlock, gold coins, a financial growth chart document, and a calculator on a navy desk — representing UCC-1 filings and business credit.
    Credit Strategy11 min read

    UCC-1 Filings: How a Lien You Forgot About Can Quietly Block Your Funding

    Ashley and Damon Boswell explain how UCC-1 filings appear on your business credit report, why they don't lower your score but still derail loan approvals, and how to find and remove zombie liens before an underwriter ever sees them.

    DA
    Damon Boswell & Ashley Boswell
    September 16, 2026
    Business credit monitoring on a navy desk with three credit report documents from different bureaus, a laptop showing credit score dashboards, gold coins, a gold pen, and a magnifying glass — representing business credit monitoring.
    Credit Strategy10 min read

    Business Credit Monitoring: What to Watch, What It Costs, and Why Ignorance Is Expensive

    Ashley and Damon Boswell compare business credit monitoring across Dun & Bradstreet, Experian Business, and Equifax Business — what each bureau offers for free, what the paid reports actually cost, and why monitoring is the difference between catching a problem early and discovering it at the underwriting table.

    DA
    Damon Boswell & Ashley Boswell
    September 13, 2026
    A fleet fuel card on a navy desk with a truck key fob, a fuel pump graphic, gold coins, a financial growth chart document, and a calculator — representing fleet and fuel cards as Tier 3 business credit.
    Funding Strategy11 min read

    Fleet and Fuel Cards: The Tier 3 Bridge Between Store Credit and Bank Funding

    Ashley and Damon Boswell explain how fleet and fuel cards work as Tier 3 of the ASAP Business Credit framework — higher-limit tradelines that report real-world operational spending and demonstrate the repayment discipline lenders want before approving six-figure capital.

    DA
    Damon Boswell & Ashley Boswell
    September 12, 2026
    SBA loan documents on a navy desk with a loan application form, a corporate binder with a gold seal, gold coins, a financial growth chart, a gold pen, and a calculator — representing SBA loan readiness.
    Funding Strategy12 min read

    SBA Loan Readiness: How a Strong Business Credit Profile Positions You for Approval

    Ashley and Damon Boswell break down what SBA 7(a) and 504 lenders actually evaluate, how a clean business credit profile strengthens your application, and why the ASAP Business Credit framework makes you a far more fundable borrower before you ever apply.

    DA
    Damon Boswell & Ashley Boswell
    September 11, 2026
    A stack of corporate credit cards in gold and navy, a financial growth chart with an upward arrow, gold coins, a calculator, a leather corporate binder with a gold seal, a gold fountain pen, and a small green plant on a navy desk — representing Tier 2 revolving store credit and business credit growth.
    Funding Strategy11 min read

    Tier 2 Revolving Store Credit: The Bridge Between Net-30 Vendors and Bank Funding

    Ashley and Damon Boswell explain why Tier 2 revolving store credit is the most misunderstood tier in the business credit journey — how it differs from Net-30 trade lines, which retailers actually report to the bureaus, and why skipping it caps your funding ceiling.

    DA
    Damon Boswell & Ashley Boswell
    September 10, 2026
    A corporate binder with a gold seal, gold pen, stacked gold coins, a financial growth chart document, a calculator, and a small green plant sprouting on a navy desk — representing the foundation of a business credit profile.
    Business Credit 10111 min read

    Your D-U-N-S Number: The Foundation Every Business Credit Profile Is Built On

    Ashley and Damon Boswell explain why the D-U-N-S number is the single most overlooked prerequisite for business credit — how to get it free, what it unlocks, and the exact sequence that turns a nine-digit identifier into six-figure funding.

    DA
    Damon Boswell & Ashley Boswell
    September 8, 2026
    Business funding documents, a gold pen, gold coins, a financial growth chart, a calculator, and a corporate binder with a gold seal on a navy desk — representing Tier 4 bank-level business funding.
    Funding Strategy10 min read

    Tier 4 Bank Funding: How to Qualify for $50,000 to $1.5M on Your EIN

    Ashley and Damon Boswell break down the final tier of the ASAP Business Credit framework — the bank-level cash credit and term loan products that unlock $50K to $1.5M+ in capital without a personal guarantee.

    DA
    Damon Boswell & Ashley Boswell
    September 7, 2026
    Corporate documents, a business credit binder, gold coins, a calculator, and a small sprouting plant on a navy desk — representing the first 90 days of building business credit with Net-30 vendor accounts.
    Credit Strategy9 min read

    Net-30 Vendor Accounts: The First 90 Days of Building Business Credit

    Ashley and Damon Boswell walk through the exact Net-30 vendor strategy ASAP Business Credit uses to establish your first trade lines with Dun & Bradstreet, Experian Business, and Equifax Business — and why the first 90 days set the ceiling on your future funding.

    DA
    Damon Boswell & Ashley Boswell
    September 3, 2026