
Business Credit Utilization: The Ratio Lenders Watch Closely — and How to Keep It Working for You
When Ashley Boswell and Damon Boswell review a client's profile before a Tier 4 funding push, one number gets scrutinized almost as closely as the PAYDEX score itself: utilization. Business credit utilization is the ratio of what your business owes on its revolving accounts compared to the total credit available across those accounts. It sounds simple, but Damon Boswell has watched otherwise strong profiles stall at underwriting because the utilization ratio told a story of overextension. At ASAP Business Credit, managing that ratio is not an afterthought — it is engineered into every tier of the framework from the first Net-30 account onward.
What Business Credit Utilization Actually Measures
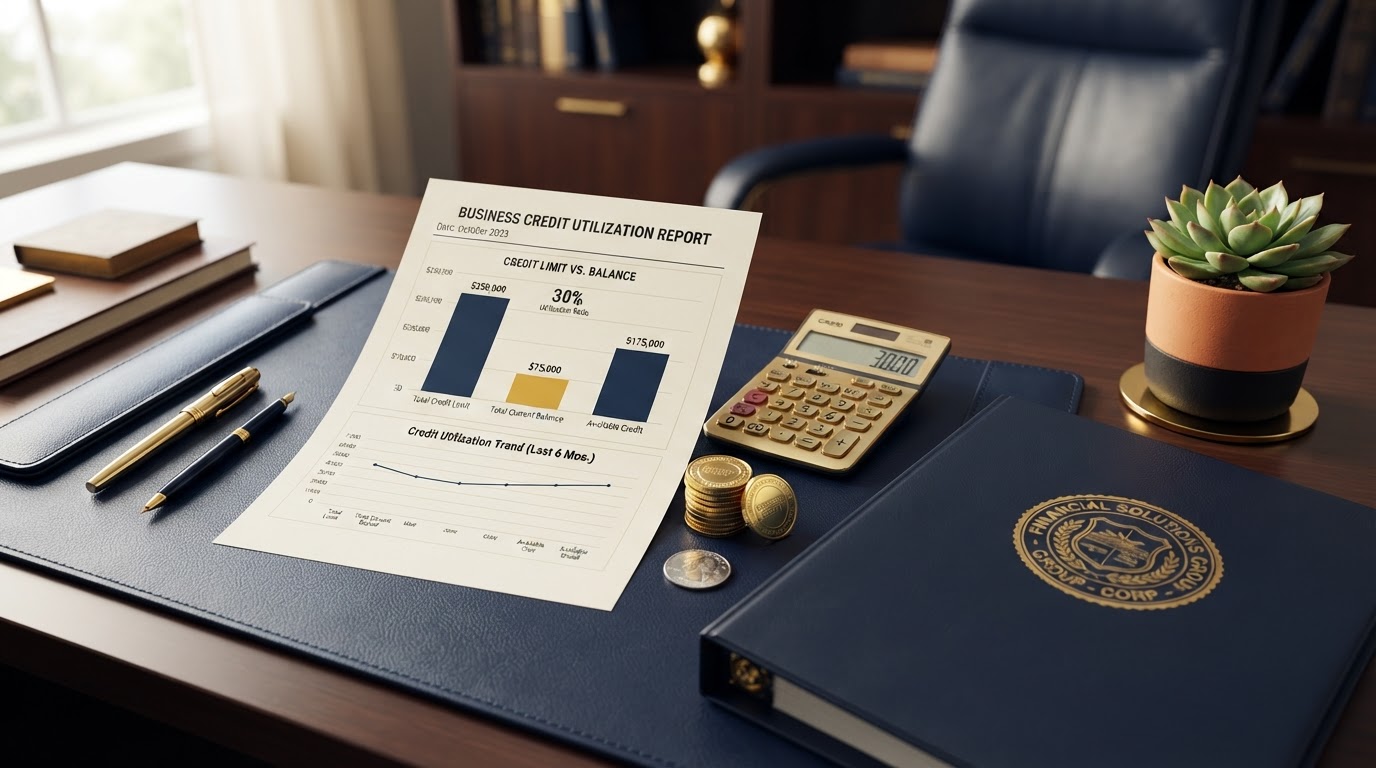
Damon Boswell defines utilization in plain terms: it is the percentage of your available revolving credit that is currently carrying a balance. If your business has $50,000 in total revolving credit limits and $15,000 in reported balances, your utilization ratio is 30%. The ratio is calculated at two levels — per individual account and across the entire profile — and lenders look at both. A single maxed-out card can drag down an otherwise healthy aggregate ratio, which is why Ashley Boswell monitors utilization account-by-account, not just in total.
- Utilization = total reported balances ÷ total credit limits, expressed as a percentage.
- It is measured both per-account and across the entire revolving profile.
- Only revolving accounts (credit cards, store credit, fleet cards) factor in — term loans and Net-30 invoices do not.
- The ratio is a snapshot based on whatever balance the issuer reported to the bureau that cycle.
How It Differs From Personal Credit Utilization
Ashley Boswell is careful to separate the two systems, because clients constantly apply personal-credit rules to business credit and get confused. On the personal side, FICO scoring treats utilization as a major factor — generally recommending you stay below 30%, and ideally closer to 10%, of your individual card limits. Business credit scoring is less transparent about the exact weight, but Damon Boswell notes that commercial bureaus and lenders still read high utilization as a signal of cash-flow strain. The key difference is that business credit profiles are evaluated more holistically alongside revenue, time in business, and industry risk — so utilization is one signal among several, but never one a lender ignores.
"Utilization is the ratio that tells a lender whether you are managing credit or surviving on it. The number on the statement matters less than the story the ratio tells."
— Damon Boswell, Master Business Credit Architect
The Thresholds Lenders Look For
Damon Boswell coaches clients toward a practical target rather than a theoretical ideal. As a general guideline, keeping aggregate business revolving utilization at or below 30% is the baseline most lenders view as healthy, with 10% to 20% considered optimal when approaching Tier 4 bank funding. Anything above 50% begins to read as overextension, and a single account reporting near its limit can trigger a manual review even when the aggregate looks fine. Ashley Boswell notes that the exact thresholds vary by lender and product — a revolving store card underwriter may be more forgiving than a bank issuing a six-figure cash credit line — which is why the ASAP method targets the conservative end of the range across the board.
- 30% or below is the widely accepted healthy ceiling for aggregate revolving utilization.
- 10%–20% is the optimal range when preparing for Tier 4 bank-level funding.
- Above 50% begins to signal cash-flow strain to lenders and bureaus.
- A single maxed-out account can trigger scrutiny even when the aggregate ratio looks acceptable.
The Reporting Timing Trap
This is the detail that trips up the most business owners, and Ashley Boswell spends real time explaining it. Utilization is calculated from whatever balance the card issuer reports to the bureau — and issuers do not necessarily report on your statement closing date. Some report the balance as of the statement date, others report on a specific day of the month, and a few report mid-cycle. That means you can pay a card down to zero every month, but if the issuer reports a high balance before your payment posts, the bureau sees high utilization for that cycle. Damon Boswell's solution is to pay down or pay off revolving balances a few days before the expected reporting date, not just before the due date, so the low balance is what actually gets reported.
"Paying on time is not the same as reporting low. The balance the bureau sees is the balance that was on the card when the issuer reported it — and that is the number you have to engineer for."
— Ashley Boswell, Business Credit Advisor
How the ASAP Framework Manages Utilization Across Tiers
Damon Boswell builds utilization management into the structure of the 4-tier system rather than treating it as a reactive fix. In Tier 1, Net-30 vendor accounts establish trade lines but do not factor into revolving utilization, so they build payment history without inflating the ratio. In Tier 2, revolving store credit is introduced with disciplined spending kept well below the limit, so the first revolving balances report in the optimal range from day one. In Tier 3, fleet and fuel cards add higher-limit revolving accounts that actually help lower aggregate utilization by expanding the total available credit denominator. By Tier 4, the profile carries a healthy spread of revolving accounts with low relative balances — exactly the picture a bank underwriter wants to see before approving $50,000 to $1.5M+ in capital.
- Tier 1 Net-30 accounts build payment history without affecting revolving utilization.
- Tier 2 revolving store credit is kept well below the limit so early balances report optimally.
- Tier 3 fleet and fuel cards raise total available credit, which lowers aggregate utilization.
- By Tier 4, the profile shows low relative balances across a healthy spread of revolving accounts.
The Credit Limit Increase Strategy
One of the most effective levers Ashley Boswell uses is the credit limit increase. Because utilization is a ratio, you can improve it from either side — lowering the balance or raising the limit. After six months of clean on-time payments on a revolving account, most issuers will consider an automatic or requested credit limit increase. A higher limit that goes unused immediately drops the utilization ratio on that account and across the aggregate profile. Damon Boswell sequences limit increases strategically, requesting them on mature accounts to expand the available-credit denominator before the next tier of applications, so the profile reads as well-capitalized rather than stretched.
Common Utilization Mistakes to Avoid
Damon Boswell sees the same mistakes repeat across profiles. The first is maxing out a new card immediately after approval to fund a purchase — that single account reports at near 100% utilization and can spook lenders even if the balance is paid off later. The second is closing old revolving accounts after paying them off, which removes that account's limit from the aggregate and can actually raise your overall utilization. The third is ignoring per-account utilization in favor of the aggregate, missing a single problem card that drags down the profile. Ashley Boswell corrects all three by keeping mature accounts open and lightly used, distributing spending across multiple cards, and paying down balances ahead of reporting dates.
- Avoid maxing out a new card immediately after approval, even if you plan to pay it off quickly.
- Do not close old paid-off revolving accounts — their limits support your aggregate ratio.
- Monitor per-account utilization, not just the aggregate, to catch problem cards early.
- Pay down balances a few days before the issuer's reporting date, not just before the due date.
From a Healthy Ratio to Six-Figure Funding
A disciplined utilization ratio is one of the quiet signals that separates a profile that gets funded from one that gets declined. Lenders want to see a business that uses credit strategically, not one that depends on it to survive. When Ashley Boswell and Damon Boswell present a profile at Tier 4, the utilization ratio is part of the credibility story — alongside a PAYDEX at 80 or above, scores across all three bureaus, and a clean payment history. If you are ready to see where your utilization stands today and how to engineer it for funding, schedule a free consultation with Ashley Boswell and Damon Boswell. We will audit your current revolving accounts, map the strategy to lower your ratio, and show you exactly how much capital your business can qualify for — all on your EIN, with your personal credit fully protected.
Ready to build your business credit profile?
Damon Boswell & Ashley Boswell and the ASAP Business Credit team will map your business to the right tier — and show you exactly how much capital you qualify for.
Schedule Your Free Consultation